
Is VT Markets legit? The ASIC claim and the real contract
VT Markets is introduced as “an Australian broker with an ASIC licence”. Read the contract carefully, though, and the accounts of Vietnamese clients do not sit under ASIC, and the UK regulator has issued a warning connected to this name.
Before we get to the contract, this is what you see when you open an account. Open vtmarkets.com from Vietnam and the browser is sent to a separate domain, vn-vtmarkets.com. The account-type table there reads:
| Account | Spread | Minimum deposit | Commission |
|---|---|---|---|
| Standard STP | 1.2 pip | 100 USD | 0 |
| Raw ECN | 0.0 pip | 100 USD | 6 USD per side |
| Cent | 1.1 pip | 50 USD | 0 |
| Cent ECN | 0.0 pip | 50 USD | 6 USD per side |
The smallest order size is 0.01 lot on all four types. The figure worth noticing is 6 USD per side on the ECN accounts: in and then out comes to 12 USD, so the 0.0 spread account only works out cheaper if you trade heavily enough.
If you have joined Vietnamese trader groups recently, you have most likely seen VT Markets turn up: IB seminars (an IB is someone who refers clients to a broker and earns a commission for it), welcome bonuses, and the familiar pitch “an Australian broker, ASIC licence”.
Some international review sites note its growth in Vietnam and Asia.
But read carefully which legal entity is named on the account-opening contract (the legal entity is the specific company that signs the contract with you), and the “Australian broker” story starts to crack.
Retail clients outside Australia (Vietnam included) cannot open accounts under the ASIC entity. They open under the South African FSCA entity or the Mauritius FSC entity.
And in 2024 the UK FCA issued a warning about VT Markets offering unauthorised CFDs to European clients with 1:500 leverage (which lets you control far more money than your real capital) through those very offshore entities.
Offshore means registered in an island jurisdiction, where supervision is much lighter.
What kind of broker is VT Markets, and what does “ASIC” in its ads mean?
VT Markets grew out of the Vantage International Group ecosystem (it was once a “sister” brand of the broker Vantage, and was later reported to have split from the group).
On licences and legal entities, the current structure is as follows:
- ASIC (Australia): no VT Markets entity appears in the licence register. Details in the section just below.
- FSCA South Africa (licence FSP 50865), mid tier (Tier-2): real supervision, but its protection and compensation mechanisms do not compare with the original FCA or ASIC.
- FSC Mauritius (GB23202269), offshore tier (Tier-3): thin supervision, no compensation fund. Many international clients are placed here.
- Cyprus, VT Markets Ltd (registration number HE436466): the broker's Vietnamese legal page says this company acts only as a payment agent for the Mauritius entity. It touches your money but is not the party that signs the contract with you.
- Dubai, CMA (licence 20200000299): a branch of the South African entity, serving a different region.
The “ASIC” label stopped applying on 13/04/2023
ASIC publishes two open datasets (08/2026 release).
The financial services licence register has 6,510 records, and none of them is VT Markets.
The authorised representative register has 363,069 records, and there the name appears in two rows:
| Representative | Under the licence of | From | To | Status |
|---|---|---|---|---|
| VT MARKETS PTY LTD no. 001260828 | VANTAGE GLOBAL PRIME PTY LTD licence 428901 | 20/12/2017 | 30/11/2022 | Ceased |
| VT MARKETS PTY LTD no. 001260828 | VINALYTICS AU PTY LTD licence 516246 | 01/12/2022 | 13/04/2023 | Ceased |
Three things follow from those two rows.
VT Markets has never held an ASIC licence. It was an authorised representative, which means it operated under another company's licence.
That status has ended, most recently on 13/04/2023, more than three years ago.
And the first company that authorised it was Vantage Global Prime, so the “split from Vantage” has a specific date: 30/11/2022.
Changing a legal structure is lawful and normal, and an ended representative status is not in itself wrongdoing. VT Markets' own Vietnamese legal page also does not mention any Australian entity.
So if you see “ASIC” attached to VT Markets, it does not come from the broker's legal page. Go back and check the source that told you so.
This is the same “two entities” model we took apart for RoboForex and IQ Option, and it should be the first thing you check with any broker.
And with VT Markets, a Tier-1 regulator (the group of strictest regulators, such as the FCA and ASIC) has spoken out about exactly this structure.
The FCA's 2024 warning: the heaviest signal in the file
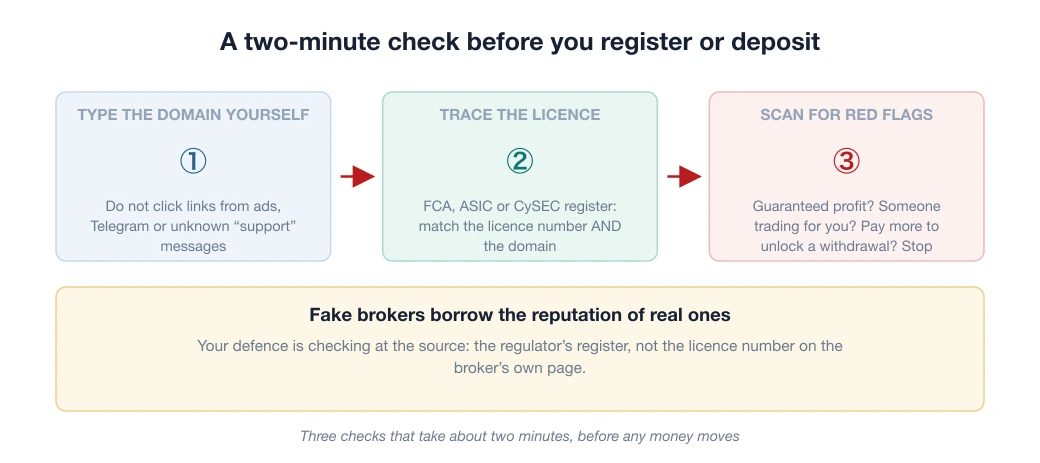
According to review sites, in 2024 the UK FCA issued a warning about VT Markets offering unauthorised CFD services to clients in Europe with leverage of up to 1:500, through an offshore entity.
For context: the FCA caps retail leverage at 1:30 because of data on accounts being wiped out on a mass scale. A broker that uses an offshore door to offer 1:500 into that market is doing what the regulator treats as getting around the fence.
A warning about “unauthorised activity in the territory” is different from a finding of fraud, and VT Markets still operates legitimately under the licences it holds.
But the message lies in the behaviour: a willingness to serve a market where it has no permission, on terms the local regulator bans. And Vietnam, a market where nobody is licensed, is where the broker's growth is running hot. How did it get that hot? The answer is a familiar one.
Japan also sent a warning letter: May 2023
Besides the UK, a second Tier-1 regulator has put something in writing about this brand.
Japan's Financial Services Agency (FSA) keeps a public list of “unregistered derivatives businesses that have been sent warning letters”. The entry for this broker reads, verbatim:
「VT Markets / インターネットを通じて、店頭デリバティブ取引の勧誘を行っていたもの / 当該業者が提供するサービスの名称は「VT Markets」である。/ 令和5年5月」
Translation: VT Markets. Solicited over-the-counter derivatives trading via the internet. The name of the service this business provides is “VT Markets”. May of Reiwa 5, that is, May 2023.
The reason given here is not being registered to operate in Japan, not a finding about how clients are treated. The list has more than 400 entries and includes many large brands.
VT Markets is on this list, with the warning letter sent in May 2023 and the activity recorded as soliciting OTC derivatives trading via the internet without registration in Japan.
Why it matters that TWO regulators have put something in writing: one warning can be a procedural matter in a single market.
Two Tier-1 regulators on two continents, years apart, recording the same pattern of soliciting local clients without registering there, describe a way of operating, not a one-off incident.
Both are warnings about unregistered activity, not findings that client money was taken. But the consequence for you is very concrete.
The FCA states plainly that clients of an unauthorised firm will have no right to complain to the ombudsman and will not be protected by the FSCS compensation scheme (the fund that pays clients when an authorised firm goes bust).
Check it yourself: open the FCA's warning page and the Japan FSA list (press Ctrl+F and type “VT Markets”). Both are the regulators' own pages.
Two regulators, two continents, updated 04/08/2026
The VT Markets file is unusual in that two Tier-1 regulators on two continents have recorded the same kind of problem:
- FCA (UK), with its own warning page for
vtmarkets.com. Clients dealing with a firm the FCA has not authorised have no right to complain to the Financial Ombudsman and are not protected by the FSCS. - Japan FSA, a warning letter in May 2023, filed under unregistered selling of OTC derivatives.
Why the “two continents” detail is worth pausing on: a single warning can be a procedural matter in one market.
Two independent regulators, half a world apart, recording the same kind of activity, offering services to local clients without registering there, point to a way of operating, not an isolated incident.
Both are warnings about unregistered activity in their own territory, not findings of fraud.
For Vietnamese readers, though, the practical consequence is still clear: if even UK and Japanese clients fall outside any protection, then Vietnamese clients, in a country that licenses no forex broker at all, fall outside it even more.
How to check yourself: open your account-opening confirmation email, read the entity name, then search that name in ASIC Connect. If you cannot find it, the “ASIC” in the ads does not apply to your account.
The VT Markets craze in Vietnam: an engine called IB
“Fast growth in Vietnam and Asia”, the shared view of observers on VT Markets, runs on a familiar machine: attractive IB commission networks, offline seminars, signal groups and deposit bonuses.
Visiting vtmarkets.com from Vietnam redirects to an alternate domain, vn-vtmarkets, a separate Vietnamese-language website for this market.
That domain's Promotions section has a campaign built specifically for the Vietnamese market, called Đấu Trường Giao Dịch IB Việt Nam (Vietnam IB Trading Arena).
The post was published on 12/08/2026 and last edited on 26/08/2026, so the campaign is live, not a leftover from an old round.
The menu label reads Bảng Xếp Hạng Top 10 IB (Top 10 IB Leaderboard), and the slogan on the page closes with the phrase “Xướng Tên Người Mạnh Nhất” (Calling Out the Strongest).
The campaign's public page publishes no rules. No ranking criteria, no prizes, no deadline.
So there is a race with a public leaderboard, while the rules can only be read by people on the inside.
The person referring you may well be on that leaderboard, and you have no way of knowing what criteria their advice is being scored on.
The same Promotions section also has a programme called Đối Tác Giỏi (Great Partner), described on the menu as Biến Doanh Số thành Giá Trị (Turning Sales into Value).
Partner contests are common and lawful in this industry, and many large brokers run them.
The contest itself is not the point. The point is that the people it affects are the only party who cannot read the rules.
What you can do right away is ask the person referring you directly: are you on any of this broker's leaderboards, and what are the scoring criteria?
Running partner contests is not wrong, but it confirms how much the broker is investing in the Vietnamese market, where, to repeat, no regulator protects traders.
When an enthusiastic IB invites you to open a VT Markets account, remember the chain of incentives: the broker pays commission based on your deposits and trading volume → the IB earns a living from that → the IB's praise is advertising, not due diligence.
Why the split from Vantage Group deserves attention
VT Markets once shared an ecosystem with Vantage, a broker we rate fairly positively for its licences and infrastructure.
The split date is in the ASIC register: the representative status under Vantage Global Prime's licence ended on 30/11/2022. The next day, 01/12/2022, VT Markets became a representative of Vinalytics AU, and that status also ended after just over four months.
WikiFX, a private monitoring site rather than a regulator, recorded a drop in its trust score after the split, along with questions about ownership transparency and the level of protection for offshore clients. That is a third party's assessment, not any regulator's finding.
Shared origins do not mean shared risk, and a broker should be judged by the entity you sign with, not by its brand relatives.
Vantage serves Vietnamese clients through its own structure; VT Markets through its FSCA/Mauritius entities; and the FCA warning file belongs to VT Markets alone.
Three of the four companies named VT Markets say they do not trade with you
The Vietnamese version of the legal page lists four entities, and three of the four state that they do not trade with you.
The South African entity states that it is not a market maker or a product issuer.
The page places it in an intermediary role and says clearly that it does not act as principal or counterparty in any of your trades.
The line for the Dubai branch is more categorical still. The page says this branch is not permitted to provide brokerage services or execute trades for clients.
It is classed as a category 5 firm, and the only work it is allowed to do is Introduction and Promotion.
The passage below is cut from the middle of the sentence the legal block devotes to the fourth entity, in Cyprus, which is why it starts with a lowercase letter:
acts only as a payment agent for VT Markets. This entity is not authorised or licensed in Cyprus and does not carry out any regulated activities.
Read the whole sentence and you have a company based in Cyprus stating that it is not licensed in Cyprus.
Put those three self-declarations together and exactly one entity is left to take your trades.
The same legal block lists the places the broker does not serve, including the United States, Singapore, India and Russia. Vietnam is not on that list.
That entire Vietnamese legal block does not mention Australia or ASIC once.
In a PAMM account, you do not set the withdrawal terms
VT Markets has one more account type that is not in the four-type table above: the PAMM account.
You put money into a shared pool, and someone else trades that capital.
With this account type, you do not decide when you can take your money out.
The broker's Vietnamese PAMM page says so plainly:
6. Can I withdraw funds from a PAMM account at any time?
Yes, investors can usually withdraw funds at specified intervals or according to the terms set by the PAMM Master.
The answer opens with “Yes”. But that “Yes” stands in front of two conditions, and the second one decides the matter.
The first refers to specified intervals, meaning there is a schedule. The second refers to terms set by the PAMM Master, meaning there is a person.
Three other answers on the same page say who that person is, and what they get to set:
- Who can be a PAMM Master: “Any experienced trader with a proven track record can apply”. The page does not say who verifies that track record.
- Minimum capital to join: it varies with the requirements of each PAMM Master. The broker sets no single level for everyone.
- Fees: the PAMM Master charges a performance fee on profits, at a rate agreed in advance.
Put those three lines together and one single person sets the terms for you to get in, sets the terms for you to get out, and takes a fee on the result in between.
PAMM is a lawful and common product, not unique to VT Markets. The broker also publishes everything above on the product page itself, and profits and losses are allocated automatically according to your share of the total pool.
The problem is not that the broker hides anything, since every sentence above is public. The problem is that answer number 6 only helps if you read it before you put money in, not when you want to take it out.
Handing capital to someone else to trade is not limited to PAMM, and we took its variants apart in the article that counted 41 profit-sharing trade-for-you offers under a single post.
Conclusion: should you use it, and if so, how?
Our verdict: VT Markets is not a ghost broker. It has real licences (FSCA/FSC), a professionally built brand and a large user community.
But it is also not “an ASIC broker” as the IBs say, it has been warned by the FCA over getting around the fence, and it serves you through an entity where, in a dispute, the complaint route is much narrower than with the Tier-1 group.
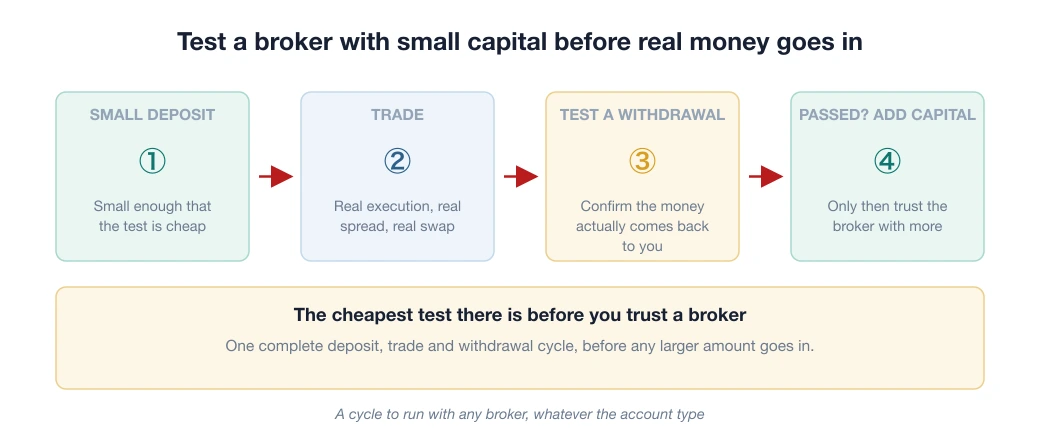
If you still use it, follow the standard rules for the medium-to-high risk group: a minimal balance, regular profit withdrawals, effective leverage of 10:1 or less, a test cycle of deposit, trade and withdraw before you trust it, and complete records.
And if you are choosing a broker and your number one criterion is “someone who steps in when something goes wrong”: our ranking of 20 brokers on 6 criteria weights the legal side most heavily. That is the one thing you cannot buy back after the problem has happened.
Frequently asked questions
Is VT Markets an ASIC broker?
No. In ASIC's two open datasets (08/2026 release), the licence register has no VT Markets entity, and the authorised representative register shows VT MARKETS PTY LTD was once a representative under another company's licence, with both statuses ceased, most recently on 13/04/2023. Vietnamese clients open accounts under the FSC Mauritius entity (GB23202269) or the FSCA South Africa entity (FSP 50865).
Has VT Markets been warned by a regulator?
Yes. In 2024 the UK FCA issued a warning about VT Markets offering unauthorised CFDs to European clients with 1:500 leverage through an offshore entity. This is a warning about unauthorised activity, not a finding of fraud.
Is VT Markets a scam?
No ruling has reached that conclusion, and the broker holds real licences (FSCA, FSC Mauritius) and has a large user community. The risk lies in the Tier-2/3 entity structure for Vietnamese clients and the warning history from the FCA. If you use it, apply the self-protection rules for the medium-to-high risk group.
Are VT Markets and Vantage the same broker?
No. The two brands once shared the Vantage International Group ecosystem but have split; each runs its own entities, licences and policies. Judge a broker by the entity you sign with, not by the brand relationship.
Are VT Markets withdrawals fast?
Withdrawal speed depends on the type of account you are using. On a normal trading account, you place the withdrawal request. On a PAMM account you do not: the broker's Vietnamese PAMM page says investors withdraw at specified intervals or according to the terms set by the PAMM Master.
- ASIC, AFS Authorised Representative open dataset (afs_rep_202608.csv, 363,069 records). VT MARKETS PTY LTD, representative no. 001260828: under licence 428901 until 30/11/2022 and under licence 516246 until 13/04/2023, both Ceased. Searched on 28/08/2026
- ASIC, AFS Licensee open dataset (afs_lic_202608.csv, 6,510 records): no VT Markets entity. Searched on 28/08/2026
- VT Markets, Vietnamese legal page (read 28/08/2026): lists four entities, Mauritius GB23202269, Cyprus HE436466 as a payment agent only, South Africa FSP 50865 and a Dubai branch. No Australian entity is listed
- FCA, official warning about VT Markets (not authorised; clients have no FSCS cover and cannot complain to the Ombudsman)
- Japan FSA, list of unregistered businesses sent warning letters (includes VT Markets, May 2023)
- WikiFX, change in VT Markets' trust score after the split from Vantage Group (private site; the regulatory warnings in this article come from the FCA and Japan FSA above)
Spotted something inaccurate? Tell us and we will check it and publish a correction.